How Much Life Insurance Do I Need With Young Kids? A Guide for Milton Families
Posted in :

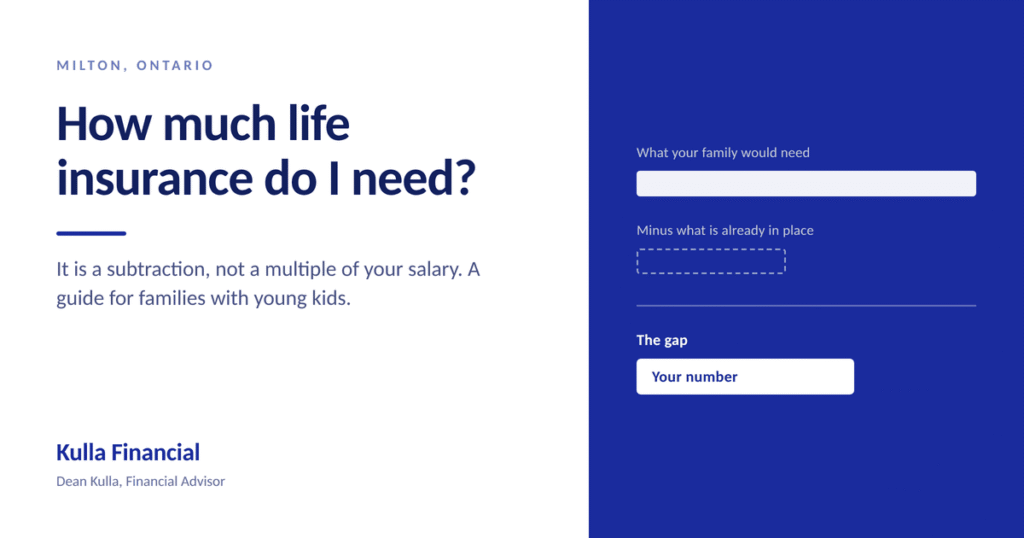
There is no standard amount, and any number you get without doing arithmetic is a guess. Life insurance is a subtraction. What your family would need if you died, minus what they would already have. If you have not sat down and done that subtraction, you don’t have a number, you have a feeling. Here is how to work it out, and what makes the Milton version of the answer different from the generic one.
The short answer
The amount is what your family would have to pay for or replace, minus the money that would already arrive. Write down the debts, the years of income, the costs that keep coming, and the final expenses. Then subtract group coverage through work, any existing policies, savings (only the portions your willing to use), and government survivor benefits. The difference is the gap.
Most families skip the subtraction, but the subtraction is where the real number lives.
Why is “ten times your income” the wrong starting point?
Because it measures the wrong thing. A multiple of income describes your salary. It says nothing about your mortgage balance, your children’s ages, or what your partner already has through their employer.
Two Milton households can earn the same and need very different amounts. One bought in 2023, still carries most of the mortgage, and has a three-year-old at home. The other has eight years left on a smaller balance and a sixteen-year-old. Identical income. Completely different gap.
A multiple is a way to start the conversation. It is not the answer.
What four numbers actually decide the amount?
Four things go on the need side of the page.
| What you are covering | What to write down | Where to find it |
|---|---|---|
| Debt that does not disappear | Mortgage balance, line of credit, car loans, anything co-signed | Your most recent mortgage statement and credit report |
| Income the household would lose | Years until your youngest is independent, multiplied by the share of household income you provide | Your last two T4s and a household budget |
| Costs that arrive anyway | Childcare, and what you intend to put toward post-secondary | Your current childcare invoices and any RESP statements |
| Final costs | Funeral, estate administration, and taxes payable on death | An estate lawyer, or a rough figure you can refine later |
Then subtract everything already in place.
| Resource | What to check | The trap |
|---|---|---|
| Group life through work | The multiple of salary in your benefits booklet, for both of you | It ends when the job ends |
| Existing individual policies | The face amount, the type, and the named beneficiary | The beneficiary may be out of date |
| Savings and investments | TFSA, RRSP and non-registered balances | Registered accounts can trigger tax on death |
| Government survivor benefits | The CPP death benefit and the CPP survivor’s pension | Both depend on contribution history, and neither is automatic |
| Home equity | Only if selling the house is genuinely realistic | For most families with young kids, it is not |
Essentially: need minus resources. The remainder is what there is to talk about.
A worked example, using made-up numbers
What follows is a hypothetical illustration with invented figures for a fictional Milton household, not a projection and not anyone real. Call them the Bakers. Two children, aged three and six. A mortgage balance of $580,000. One parent earns $85,000 and the other $70,000. Fifteen years until the youngest turns eighteen.
They decide to cover the mortgage in full, replace ten years of the higher income, set aside $60,000 for childcare and education, and allow $25,000 for final costs. That is a need of $1,515,000. Against it they have $170,000 of group coverage and $40,000 in savings, which leaves a gap of roughly $1,305,000.
Those are invented numbers for an invented family. The arithmetic is deliberately simple and ignores inflation and any growth on invested money, both of which move the answer. Your own figures, and the assumptions worth making about them, are the part that needs a conversation rather than a blog post.
Why is the Milton version of this question different?
Milton is young, well paid and growing quickly, all at once. At the 2021 Census the town had 132,979 residents, an average age of 35.2, a median household income of $126,000 for the 2020 income year, and 24% of the population under fifteen. It had also grown 20.7% in the five years to 2021, so the current figures are higher than those. (Statistics Canada, 2021 Census Profile, Milton)
Growth on that scale means a lot of Milton households bought recently. If you bought in the last few years, most of that mortgage balance is still outstanding, and the size of it assumed both incomes would keep arriving.
That is the situation I see most often in fact-finds here. Two incomes, both load-bearing, childcare running alongside the mortgage, and a household that looks comfortable on paper with very little slack in it.
The practical consequence is the one most families miss. When both incomes are required to hold the house, the lower earner is not the optional one. Losing either income breaks the same budget.
Milton is also a town of newcomers. At the 2021 Census, 42.1% of residents were immigrants and a further 1.6% were non-permanent residents. (Statistics Canada, 2021 Census Profile, Milton) A short medical history in Canada changes how an application is assessed, and it is worth raising at the start rather than discovering it partway through.
None of this is unusual nationally. In the 2023 Canadian Insurance Barometer Study, 31% of Canadian adults, around 8.4 million people, said they need life insurance or need more of it than they have. (LIMRA and Life Happens, reported 2024) That is people saying it about themselves, which is worth knowing. Most of them have not worked out the number.
What do most people get wrong?
Counting group coverage as permanent. Coverage through an employer usually ends when the job does. If it is doing the heavy lifting in your plan, your plan is tied to your job.
Insuring only the higher earner. In a two-income Milton household that leaves the same mortgage exposed from the other direction. Work out both sides.
Leaving the beneficiary designation alone. A policy bought before the kids may still name a parent or a former partner. It takes ten minutes to check. Do it while the paperwork is already out.
Choosing the amount that fits the budget, then calling it the need. Work out the need first. Then decide what to do about it. Those are two separate decisions, and merging them hides the size of the gap.
Assuming mortgage insurance from the lender is the same product. Creditor mortgage insurance is generally tied to the loan and pays the lender. An individual policy pays the beneficiary you name and is not tied to the property. They work differently, and its always better for your family to have the money to decide your next steps.
Treating life insurance as the whole protection question. Life insurance pays out on death. It does nothing if you survive an illness that stops you working, which is the job critical illness and disability coverage do. Worth knowing which gap you are actually closing.
Protection sits early in the 7 Pillars of Generational Wealth for the same reason. Everything built after it depends on its holding.
Questions people ask
Does a stay-at-home parent need coverage?
It is worth working out rather than assuming. The work still has to be done if that parent is not there, and the surviving parent either pays someone to do it or gives up hours to do it themselves. Price both against your own childcare invoices and see what the number looks like.
Is the coverage through my job enough?
Check the multiple in your benefits booklet against the gap you calculated. Group coverage is usually a set multiple of salary, which is a rule of thumb wearing a different hat. It also ends with the job.
Term or whole life?
They answer different questions. Term covers a defined period, which suits a mortgage and a set of dependent years. Permanent coverage lasts as long as the policy stays in force and does other jobs beside. Neither is better in the abstract, and choosing between them without knowing your situation is guessing.
I bought a policy before the kids arrived. Is it still right?
Possibly not. The amount was set against a smaller mortgage and no dependants. Check the face amount, the type and the beneficiary at the same time.
I am new to Canada and have a short medical history here. Does that matter?
It can affect how an insurer assesses the application, and it is better raised at the start. Whether coverage is offered, and on what terms, is the insurer’s decision.
What to do next
Two options, depending on where you are.
If you want to work out your own number first, get the family coverage worksheet emailed to you. It is the same need-minus-resources page above, laid out so you can fill it in at the kitchen table.
If you would rather work through it with someone, book a time. It’s a conversation about your situation rather than a sales appointment. The point is to get you to the number, whether or not you do anything else about it.