Disability Insurance in Milton, Ontario
Disability insurance replaces part of your income if you cannot work because of illness or injury. It is the coverage most households skip and the one that protects the asset everything else depends on, which is your ability to earn. This page explains the four contract terms that decide whether a policy actually pays, and what changes if you are self-employed.
I’m Dean Kulla, a Financial Advisor, and Owner of Kulla Financial in Milton. I’m licensed in Ontario for life and accident and sickness insurance, and I am a mutual fund dealing representative with Sterling Mutuals Inc.
The four terms that decide everything
People shop for disability coverage on the monthly benefit amount. The benefit amount is the least important of the five numbers in the contract.
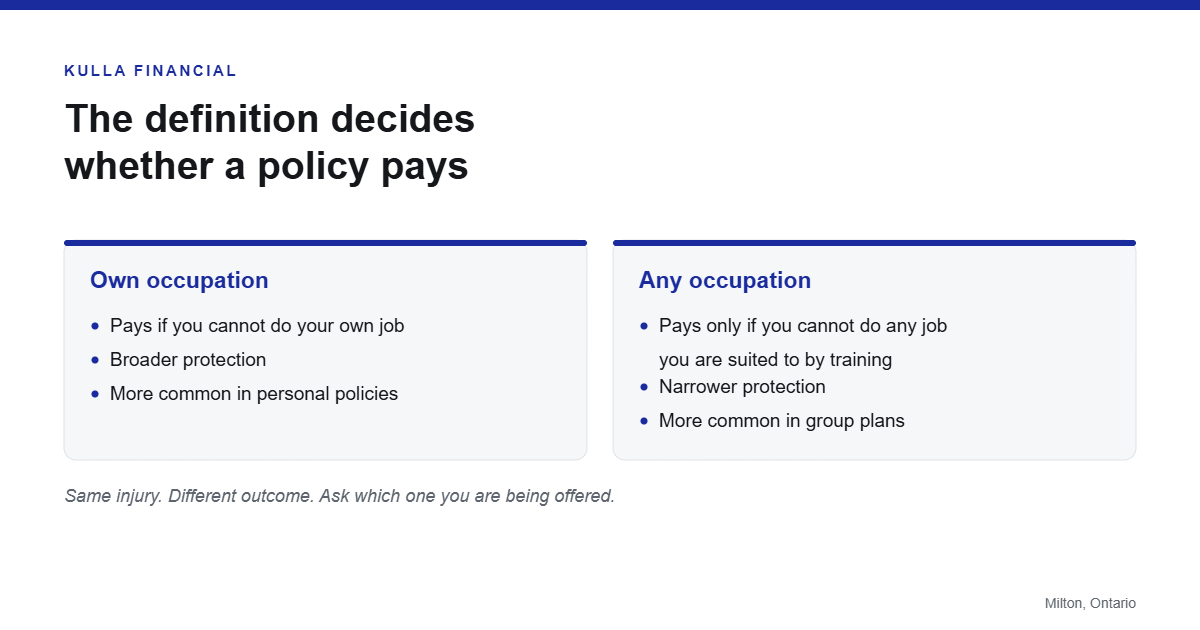
The definition of disability. This is the one that matters most. Some contracts pay if you cannot perform the duties of your own occupation. Others pay only if you cannot perform the duties of any occupation you are reasonably suited to by training and experience. A surgeon who can no longer operate but could teach is covered under the first definition and may not be under the second. Some contracts use one definition for an initial period and switch to the other after that.
The elimination period. How long you must be disabled before benefits start. A longer wait lowers the cost and means you carry more of the early months yourself, which is a savings question as much as an insurance one.
The benefit period. How long payments continue once they start. Options typically run from a short fixed term to age 65. A policy that pays for two years and a policy that pays to 65 are different products.
Whether the insurer can change the contract. On some policies the terms and the cost are locked once issued. On others the insurer can adjust pricing for an entire class of policyholders. Ask which one you are being offered.
The benefit amount itself is set as a portion of your earned income, and the insurer sets the maximum it will offer based on your income when you apply. That is why the amount is the last thing to settle, not the first.
Group coverage through work, and where it stops
If you have long term disability coverage through an employer, read the booklet before buying anything. Then check these five things, because they are where group and personal coverage diverge.
The definition. Group plans more often use the any occupation test, or switch to it after a period.
Portability. Group coverage ends when the job ends. Personal coverage does not.
Whether the benefit is taxable. This generally depends on who paid the premiums. Where the employee paid, benefits are generally received tax free; where the employer paid, they are generally taxable. A taxable benefit and a tax free benefit of the same headline amount are not the same money, so confirm which applies to your plan.
Offsets. Group plans commonly reduce what they pay by other benefits you receive, including CPP disability.
The cap. Group maximums are often set at a level that suits a median salary and falls short for higher earners or for income that includes bonus or commission.
If you are self-employed
You have no group plan, no sick leave, and no employer topping anything up. You are also harder to underwrite, because the insurer has to establish what your income actually is.
That means the application asks for tax documentation, and the benefit is assessed against net business income rather than gross revenue. Business owners are frequently surprised by the gap between the two. It is worth knowing the number the insurer will use before you start, rather than after.
There are also contracts written specifically to cover business overhead, which is separate from covering your personal income. If you have premises, staff or equipment payments that continue whether or not you can work, that is a distinct conversation.
What this looks like in Milton
Milton households mostly carry a recent mortgage against two working incomes, which is the profile where an income interruption does the most damage.
At the 2021 Census the town had 132,979 residents, an average age of 35.2, and had grown 20.7% since 2016. Median household income was $126,000 for 2020. (Source: Statistics Canada, 2021 Census Profile, Milton.)
Life insurance gets bought in households like this and disability coverage often does not, which is backwards on frequency. An earner is considerably more likely to be off work for a year than to die in any given year.
What most people get wrong
Shopping on the monthly amount. A large benefit under an any occupation definition can be worth less than a smaller benefit under an own occupation definition. Compare the definitions first.
Assuming CPP disability fills the gap. It has a strict test, it depends on your contribution history, and group plans often offset against it. It is a floor, not a plan.
Waiting for a health event to think about it. This is the most heavily underwritten of the common personal products. Health history is assessed at application.
Forgetting to insure a non-salary income. Commission, bonus, dividends and self-employment income are all treated differently on an application. If most of your income is not salary, say so at the start.
Whether an insurer offers you coverage, and on what terms, is the insurer’s decision after it reviews your application, your medical history and your income documentation.
Questions people ask
How long does the application take?
Longer than life insurance, usually. It commonly involves a medical questionnaire, possible bloodwork or a paramedical exam, and income documentation. Plan in weeks rather than days.
Can I have both group and personal coverage?
Often yes, but insurers look at your total coverage across all sources when deciding what they will issue, so the group plan affects what a personal policy can add.
Does it cover mental health absences?
Many contracts do, and many limit how long they will pay for them. This is a specific thing to check in the wording rather than assume either way.
What if I go back to work part time?
Some contracts include partial or residual benefits that pay while you are working at reduced capacity. Others are all or nothing. It is a real difference between products.
Is critical illness insurance the same thing?
No. Critical illness pays a lump sum on a listed diagnosis whether or not you stop working. Disability pays monthly while you cannot work. See critical illness insurance.
What to do next
Book a fact-finding appointment. We establish what income the insurer would actually consider, what your group plan already does, and which definition of disability you are being offered.
Book an appointment with Dean Kulla
If you would rather talk first, call 905-636-4401 or email dean.kulla@kullafinancial.com.
This page is general information, not advice. It does not consider your situation, and your situation is the part that decides the answer. Whether a claim is payable is determined by the wording of your own policy. Dean Kulla is a Financial Advisor with Kulla Financial, licensed in Ontario for life and accident and sickness insurance, and a mutual fund dealing representative with Sterling Mutuals Inc. Insurance products are provided independently by Dean Kulla and are not the business of Sterling Mutuals Inc.
Rules and program details change. Check the source links before relying on anything here. Last updated 14 September 2026.