High Risk Life Insurance in Milton, Ontario
Being turned down or charged extra by one insurer does not mean you are uninsurable. Insurers assess the same medical history differently, and a decline is a decision by one company rather than a verdict from the market. This page explains what a rating and a decline actually are, what drives them, and what the routes are if standard coverage is not available to you right now.
I am Dean Kulla, a Financial Advisor with Kulla Financial in Milton. I am licensed in Ontario for life and accident and sickness insurance, and I am a mutual fund dealing representative with Sterling Mutuals Inc.
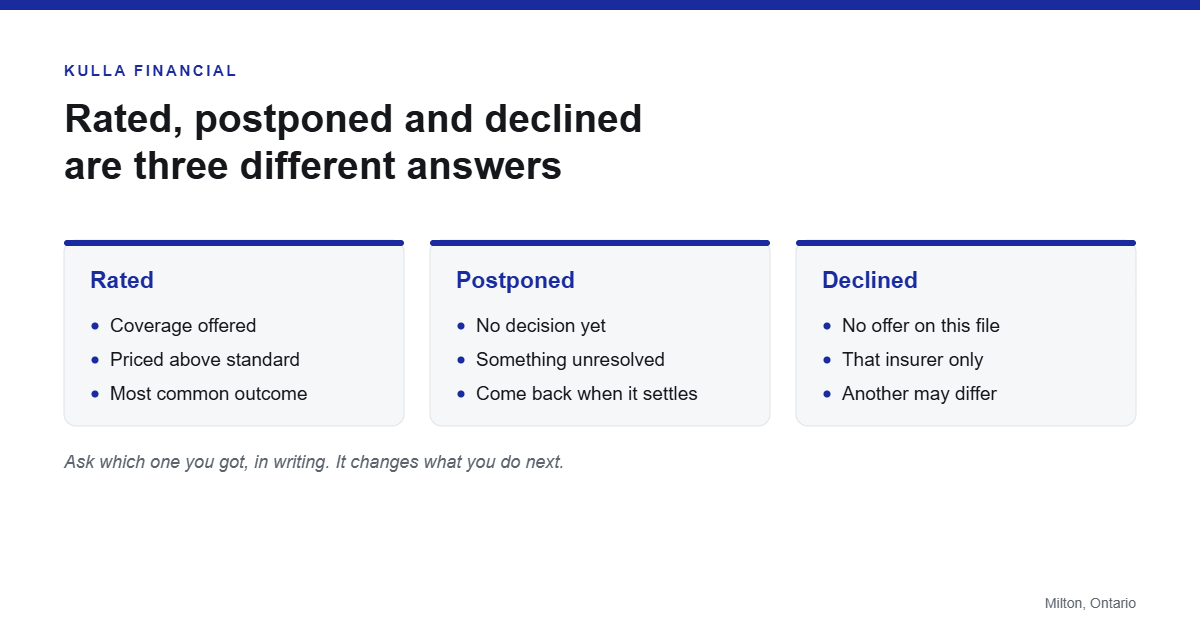
Rated, postponed, declined: three different outcomes
They get talked about as one thing and they are not.
Rated. The insurer will offer coverage, at a higher cost than standard, because it assesses your file as carrying more risk. This is by far the most common of the three and it is a normal offer, not a rejection.
Postponed. The insurer will not make a decision yet, usually because something is unresolved: a test pending, a recent diagnosis, a surgery too recent to assess, a condition that needs a period of stability first. Postponed means come back, and it often means come back in six or twelve months.
Declined. The insurer will not offer coverage on this application. It applies to that insurer and that application. Another insurer may take a different view, and the underwriting appetite for particular conditions genuinely varies between companies.
Knowing which of the three you got changes what you should do next, so it is worth asking for it in writing.
What actually drives the assessment
Life insurance underwriting in Canada looks at a defined set of factors. Knowing which one is driving your file tells you whether it is fixable.
Age. Not fixable, and it moves in one direction, which is why postponing an application rarely helps.
Nicotine use. Cigarettes, vaping, cannabis and nicotine replacement are all assessed, and the definitions and look-back periods differ by insurer. This is one of the largest single factors and it is one that can change over time.
Current health and medical history. What you have been diagnosed with, what you are treated for, how well controlled it is, and how long it has been stable. Control and stability matter as much as the diagnosis itself.
Family history. Certain conditions in parents or siblings at early ages are assessed, particularly cardiac and some cancers.
Height and weight. Assessed against the insurer’s own table, which varies between companies more than people expect.
Occupation and hobbies. Some work and some activities are rated or excluded, including aviation, diving, climbing and motorsport. An exclusion for a specific activity is sometimes available where a rating is not.
Driving record and travel. Impaired driving convictions are assessed, and so is planned travel or residence in certain regions.
One thing that does not drive it, contrary to a lot of what is written online: your postal code is not a rating factor in Canadian individual life underwriting.
The routes when standard coverage is not available
Three, roughly in order of how much coverage they make available.
Fully underwritten with a rating. A normal policy at a higher cost. This gives you the most coverage and the broadest options, and it is where to start unless something rules it out.
Simplified issue. A shorter application with a limited set of health questions and no exam. Coverage amounts are capped lower than fully underwritten policies, and eligibility still depends on how you answer.
No-medical coverage. Issued with very few health questions. Amounts are smaller again, and these contracts commonly limit what is payable in the first policy years, so read that clause specifically before relying on it.
A rating is also not necessarily permanent. Many insurers will review a rating after a defined period of stability, better test results, or time since an event. If you are currently rated, ask what the insurer’s reconsideration process is and what evidence it wants.
What to do before you apply again
Get the reason in writing. You are entitled to know the basis of the decision. It is difficult to fix a file without it.
Get your own records. Your doctor’s notes are what the insurer is reading. People are regularly rated on something recorded years ago that is no longer accurate, or on a note that reads worse than the situation.
Do not apply to five insurers at once. Insurers share underwriting information through an industry exchange, so a run of applications in a short window is visible to the next one and rarely helps.
Check what you already have. Group coverage at work usually involves no individual underwriting, and many group plans allow you to convert or increase coverage without medical evidence at defined points. That is frequently the most overlooked option for someone who has been declined.
What this looks like in Milton
The practical reason this page exists is that an independent advisor can approach several insurers, and a single-company representative cannot.
Milton had 132,979 residents at the 2021 Census with an average age of 35.2. (Source: Statistics Canada, 2021 Census Profile, Milton.) A young town means most people applying here are applying for the first time, and a first decline is often taken as final when it is not.
Whether any insurer offers you coverage, and on what terms, is that insurer’s decision after it reviews your application and your medical evidence. I cannot promise an outcome, and neither can anybody else. What I can do is take the file to more than one company and tell you honestly what the answers were.
Questions people ask
I was declined. How long should I wait to reapply?
It depends entirely on the reason. If it was postponed pending a test, the insurer usually tells you when to come back. If it was a recent event, stability over time is what changes the assessment. Reapplying immediately with nothing changed is unlikely to produce a different answer.
Will a decline follow me between insurers?
Underwriting information is shared through an industry exchange, so your application history is visible. That is a reason to prepare a file properly rather than to apply widely and hope.
If I quit smoking, when does that change things?
Insurers apply their own look-back periods before classifying someone as a non-smoker, and those periods differ between companies. It is worth asking the specific question rather than assuming a single industry rule.
Can I get critical illness or disability coverage if I have been rated for life insurance?
Those products are underwritten separately and more strictly. A life insurance rating does not automatically decide them either way. See critical illness insurance and disability insurance.
Is it worth taking a rated policy or should I keep shopping?
If coverage is offered and you need coverage, having something in force while you explore alternatives is generally the better sequence. Cancelling or declining an offer first can leave you with nothing.
What to do next
Book a fact-finding appointment and bring whatever the insurer sent you. We work out which of the three outcomes you actually got, what is driving it, and which companies are worth approaching.
Book an appointment with Dean Kulla
If you would rather talk first, call 905-636-4401 or email dean.kulla@kullafinancial.com.
This page is general information, not advice. It does not consider your situation, and your situation is the part that decides the answer. Whether coverage is offered, and on what terms, is the insurer’s decision. Whether a claim is payable is determined by the wording of your own policy. Dean Kulla is a Financial Advisor with Kulla Financial, licensed in Ontario for life and accident and sickness insurance, and a mutual fund dealing representative with Sterling Mutuals Inc. Insurance products are provided independently by Dean Kulla and are not the business of Sterling Mutuals Inc.
Rules and program details change. Check the source links before relying on anything here. Last updated 14 September 2026.