Children’s Life Insurance in Milton, Ontario
Children’s life insurance is a policy on a child’s life, owned by a parent or grandparent. It is a legitimate product with three real uses, and for most families it is not the first thing to buy. This page covers both halves of that honestly, because the reasons to say no are as useful as the reasons to say yes.
I am Dean Kulla, a Financial Advisor with Kulla Financial in Milton. I am licensed in Ontario for life and accident and sickness insurance, and I am a mutual fund dealing representative with Sterling Mutuals Inc.
Start here: it is usually not the first priority
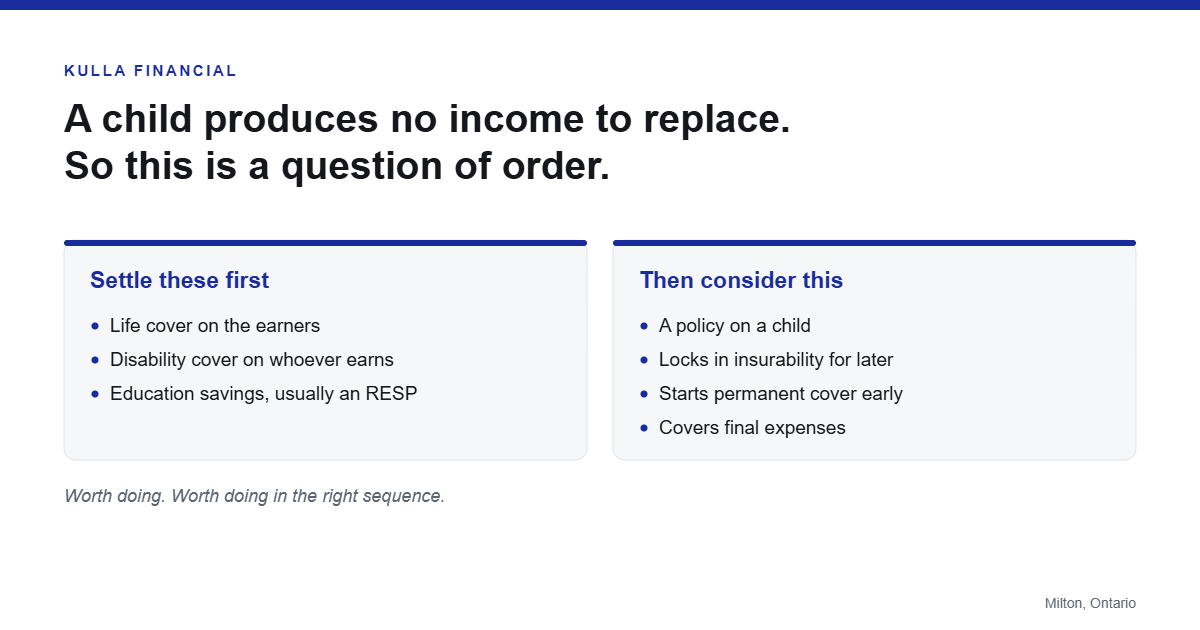
A child does not produce income, so there is no income to replace. That is the honest starting point and it is why this product sits further down the list than most websites selling it suggest.
For a household with young children, the coverage that protects those children is coverage on the parents’ lives, plus disability coverage on whoever earns. If either of those has a gap, that gap comes first. Money set aside for education is a separate question again, and a Registered Education Savings Plan is the usual vehicle for it because of the federal grant attached.
If those are handled and you are still interested, the rest of this page is the actual case.
The three reasons parents do it
Insurability later in life. This is the main one. A policy issued now is not re-underwritten later because of a health condition that develops in between. Children’s policies commonly include an option to increase the coverage at set points in adulthood without new medical evidence. If a family has a history of a condition that tends to appear in early adulthood, this is the reason that carries the most weight. Whether a child qualifies for coverage now is still the insurer’s decision after it reviews the application.
Starting permanent coverage early. A permanent policy stays in force as long as it is maintained and holds a cash value the owner can access. Started in childhood, the premium is set against a child’s age and the policy has a long time to accumulate that value. Whether this is a sensible use of the money compared with other options is a real question and the answer is not automatic.
Final expenses. Nobody wants to plan for this and it is the least discussed reason. Where a family would face funeral costs and time away from work in the worst circumstance, a small policy covers it. It is a legitimate reason and it does not need dressing up.
How the policy is actually structured
Three roles, and people mix them up.
The insured is the child. The owner is the adult who applies, pays and controls the policy, usually a parent or grandparent. The beneficiary is whoever receives the benefit, normally the owner.
Ownership can usually be transferred to the child once they reach adulthood, which is how these policies are most often intended to end up. That transfer has tax consequences worth understanding before it happens rather than after, and it is a question for your accountant as much as for me.
Coverage is also frequently available as a rider on a parent’s own policy rather than as a standalone contract. That is often the simpler route where the goal is modest coverage rather than building a permanent policy, and it is worth asking about.
What to check before buying
Four things, in this order.
Whether the parents’ coverage is complete first. If there is a gap on an earner, this purchase is out of sequence.
What the future increase option actually says. If insurability is your reason, the value of the policy is entirely in this clause. Read how much can be added, at what ages, and on what conditions.
Whether it is term or permanent. Term coverage on a child expires. Permanent coverage does not. These are different purchases with different reasons behind them.
What happens if you stop paying. Ask specifically. The answer differs between term and permanent policies and it is the question people wish they had asked.
What this looks like in Milton
Milton has proportionally more children than most Ontario towns, which is why this question comes up here more than the product’s overall popularity would suggest.
At the 2021 Census roughly a quarter of Milton residents were under 15, the average age was 35.2, and the town had grown 20.7% since 2016 to 132,979 residents. (Source: Statistics Canada, 2021 Census Profile, Milton.)
A town this young is also a town where a lot of parents are still working through the first round of their own coverage. That is the sequence worth getting right.
What most people get wrong
Treating it as an education savings plan. It is life insurance. An RESP exists for education specifically and carries a federal grant that insurance does not. Comparing them as if they do the same job leads to the wrong choice.
Buying it before the parents are covered. The most common sequencing error on this topic.
Assuming a grandparent can just take out a policy. There has to be an insurable interest and the parents are normally involved in the application. Sort that out before committing to anything at a birthday.
Ignoring the transfer. Ownership passing to the child at adulthood is a taxable event in some circumstances. Plan for it at the start.
Questions people ask
At what age can a child be insured?
Most insurers will consider a child from a few weeks old, and the specific minimum varies between companies. There is no single answer across the market.
Does my child need a medical exam?
Usually not. Applications for children are typically based on a health questionnaire and the family history, rather than an exam.
Can I get coverage for a child with an existing health condition?
Sometimes, sometimes on modified terms, and sometimes not. It depends on the condition and the insurer, and it is worth asking rather than assuming the answer. See coverage when you have been rated or declined.
Is the benefit taxable?
A death benefit paid to a named beneficiary is generally received tax free. The tax treatment of accessing cash value, or of transferring ownership, is a different question and depends on your circumstances.
What happens to the policy when my child turns 18?
Nothing automatically. The owner still owns it. Transferring it to the child is a deliberate step, and worth planning for its tax consequences.
Is it better to add a child rider to my own policy?
Often simpler, if the goal is modest coverage. A standalone permanent policy does a different job. Which fits depends on your reason for buying.
What to do next
Book a fact-finding appointment. We will check the sequence first, which means your own coverage, and then look at whether a policy on your child does something you actually want.
Book an appointment with Dean Kulla
If you would rather talk first, call 905-636-4401 or email dean.kulla@kullafinancial.com.
This page is general information, not advice. It does not consider your situation, and your situation is the part that decides the answer. Whether a claim is payable is determined by the wording of your own policy. Tax treatment depends on your circumstances and is a matter for a qualified tax advisor. Dean Kulla is a Financial Advisor with Kulla Financial, licensed in Ontario for life and accident and sickness insurance, and a mutual fund dealing representative with Sterling Mutuals Inc. Insurance products are provided independently by Dean Kulla and are not the business of Sterling Mutuals Inc.
Rules and program details change. Check the source links before relying on anything here. Last updated 14 September 2026.